Cash-flow pressure
A homeowner wants to understand whether replacing an existing mortgage could reduce required monthly principal-and-interest payments. Taxes, insurance and upkeep still have to be paid.
 Founded 1989
A reverse mortgage can create borrowing capacity. Help your client compare the trade-offs before deciding.
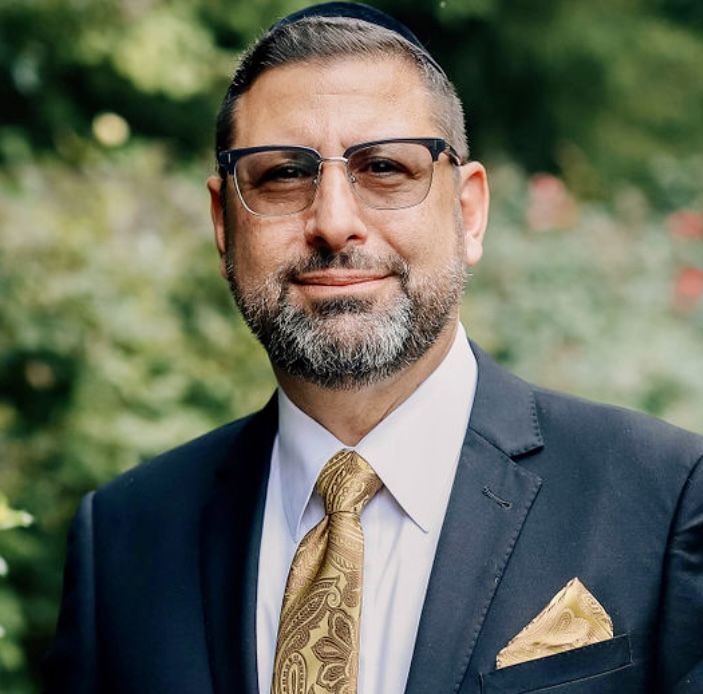
Work directly with Carl Guzman, CPA, founder of Greenback Capital. He has spent 37 years in the mortgage business. The conversation starts with the client's goals, costs and obligations, including when a reverse mortgage may not fit.
Start with a general question or an anonymized outline. Do not email client names, Social Security numbers, statements or other sensitive financial information. Arrange an approved secure channel before sharing client details.
A homeowner wants to understand whether replacing an existing mortgage could reduce required monthly principal-and-interest payments. Taxes, insurance and upkeep still have to be paid.
A client wants access to funds while keeping savings or investments. Compare loan costs and a growing debt balance with the cost and risk of using those assets instead.
A client is weighing cash, a forward mortgage and a HECM for purchase. Compare upfront cash, ongoing obligations and how long the client expects to stay.
HYPOTHETICAL EDUCATIONAL EXAMPLE · NOT A CLIENT RESULT OR LOAN QUOTE
A 72-year-old homeowner has a $900,000 principal residence, no property liens and $300,000 in liquid savings. They want to spend $100,000 on home improvements. This example compares where the money comes from, not which choice is best.
For the borrowing paths only, assume the homeowner qualifies and the loan can provide $100,000 net after any required payoffs and financed costs. That is an assumption, not an eligibility result. HECM principal limits, financial assessment, reserves and first-year withdrawal limits must be checked before relying on that amount.
$300,000 − $100,000 = $200,000.
No new home-secured debt or loan closing costs. The client has less liquid savings available for other needs.
New debt is $100,000 plus any financed costs. Required monthly principal-and-interest payments affect the budget.
Obtain actual rates, fees, payment terms and qualification results before comparing total cost.
New debt is $100,000 plus any financed costs. No required monthly principal-and-interest payments while loan obligations are met.
Interest, mortgage insurance and applicable fees add to the balance over time if not paid. Taxes, insurance, maintenance and principal-residence requirements remain.
Borrowing preserves liquidity by adding debt secured by the home. It does not make the $100,000 expense disappear. Investments can lose value, and loan costs can exceed investment returns. This example does not assume an investment return, tax benefit, home appreciation or future loan balance.
No interest rate, APR, monthly loan payment or closing-cost quote is offered here. Savings figures exclude cash-paid loan fees. Financed fees increase debt and reduce home equity. A personalized comparison needs actual loan terms, the client's full budget, time horizon and alternatives.
An adjustable-rate HECM may offer a line of credit. Growth in unused borrowing capacity is not interest earned on an investment or an increase in home equity. Drawing funds creates debt. Fixed-rate lump-sum HECMs do not have a credit-line growth feature.
A short time in the home, difficulty paying property charges, limited remaining equity, a need to preserve equity for a later move, or a lower-cost alternative can change the answer. A HECM requires HUD-approved counseling. Failure to meet loan obligations can lead to default and foreclosure.
Discuss the client's objective and the alternatives with Carl before moving to an application. Begin without identifying the client.
General HECM information checked November 11, 2026. The scenario above is illustrative, not a statement of current market loan terms.
General information only, not financial, tax or legal advice, a loan offer or a commitment. Eligibility and program terms apply.
No. It is a loan secured by your home. You owe the amount borrowed plus interest and fees. The balance generally grows over time, reducing the equity left in your home.
For a HECM, you must keep the home as your principal residence, pay property taxes and insurance, and keep it in good repair. Other property charges may apply. Not meeting loan obligations can lead to default and foreclosure. Requirements vary by program.
Reverse mortgages typically become due when the borrower dies, sells the home or no longer uses it as a principal residence, subject to applicable borrower and eligible-spouse protections. Failure to meet loan obligations can make repayment due sooner. Review the specific terms before deciding.
Keeping investments does not guarantee they will gain value. A business can lose money. Using home equity for either purpose creates a home-secured debt that remains even if the investment or business does not succeed. Review the risks and alternatives with appropriate financial, tax and legal advisers.
Discuss your questions with Carl, or continue to our secure portal.
Opens Greenback Capital's secure point-of-sale portal. No application data is collected on this page.
Do not email Social Security numbers, bank statements or sensitive documents. Use an approved secure channel.